
Scotiabank upgrades Paramount Resources, cites steep discount to peers
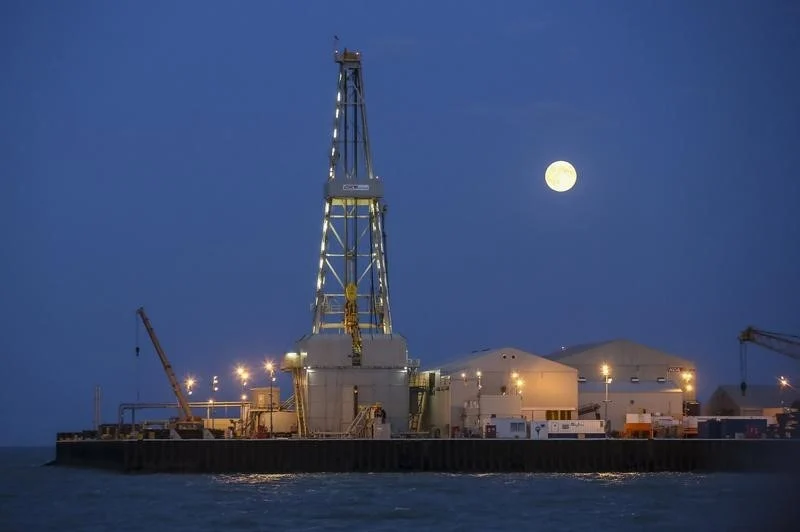
Scotiabank has become more constructive on a Canadian energy producer, saying the recent divestiture of an asset has streamlined its operations, improved its growth runway and left the shares trading well below comparable companies.
The brokerage lifted Paramount Resources Ltd. (TSX:POU) to Sector Outperform from Sector Perform and increased its price target to C$42 from C$40. The revised target suggests about 34% upside from the C$31.29 share price referenced in the November 9 research note.
Analyst Chris MacCulloch said Paramount’s sale of its Kaybob assets to Outwest Energy reflects fair value for relatively mature properties that carry high operating costs and related abandonment liabilities. Paramount will keep a 49% equity stake in those assets through Outwest.
The deal also releases capital that can be directed toward faster development of Alhambra Phase 3 and the Hoole project, giving Paramount a clearer route to its next growth phase.
Valuation forms another central element of the bullish case. Scotiabank calculates that Paramount trades at only 4.5 times its estimated 2028 debt-adjusted cash flow, versus 6.3 times for Canadian peers.
The brokerage projects a 24% compound annual growth rate in debt- and dividend-adjusted per-share value from 2027 to 2030, well ahead of the 11.6% it forecasts for Canadian peers.
Scotiabank also lifted its net asset value estimate to C$45.29 per share from C$42.05, strengthening its view that the stock presents an attractive investment opportunity.
Read also
CNN reports NSA IT outage disrupts Georgia site backing Middle East operations
An IT outage at the National Security Agency has affected operations at a Georgia facility…
Read More
Hedge funds weigh Europe-over-US volatility trade after S&P 500 options repricing
Equity derivatives desks are considering buying European volatility and selling US volatil…
Read More
Kornit Digital Stock Tumbles as Q4 Guidance and Limited 2027 Visibility Weigh
Kornit Digital shares fell sharply after an early pre-market rally reversed when Q4 guidan…
Read More